How to become a SEPA indirect participant: What you need to know

If you want to know how to become a SEPA indirect participant, you’ve probably already realised that direct participation can be extremely resource intensive. Beyond the initial timelines and investment, you also need to maintain ongoing access to the scheme, which requires significant internal expertise and attention.
With indirect participation, you can gain greater control over your institution’s SEPA presence and payment operations – without the cost of building the full clearing and settlement infrastructure yourself.
But becoming a SEPA indirect participant involves more than just connecting to a sponsor bank. You may need to:
- Get a BIC so your institution can be identified and reached across SEPA
- Be compliant with European Payments Council (EPC) and regulatory requirements, as a direct participant.
- Establish the right settlement and liquidity arrangements
- Integrate with your sponsor bank’s infrastructure
- Prove that your systems are ready to process payments reliably
The sponsor bank you choose shapes much of that process, including how quickly you launch and how easily you can scale afterwards. So, when considering becoming an indirect participant, it’s worth carefully evaluating potential sponsor banks. And as SEPA Instant becomes more widely adopted, your sponsor bank’s ability to support reliable 24/7 payments will matter even more.
In this article, we’ll cover:
- Why SEPA Instant is becoming the default for euro payments
- Direct vs indirect SEPA participation: What’s the difference?
- How to become a SEPA indirect participant
- What to look for in a SEPA sponsor bank
- Why choose ClearBank for SEPA indirect participation?
- Case study: How FuturePay expanded EUR and GBP collections with ClearBank
ClearBank helps regulated financial institutions access SEPA through cloud-native banking and payment infrastructure. To explore indirect SEPA participation with ClearBank, get in touch.
Why SEPA Instant is becoming the default for euro payments
The EU Instant Payments Regulation (IPR) has made the sending and receiving of instant euro payments mandatory for most euro area payment service providers.
The IPR introduces phased requirements for payment service providers to send and receive instant euro credit transfers, alongside measures such as fee parity and Verification of Payee.
This changes the decision for EMIs, PIs, and banks. SEPA Instant can no longer be treated as a future enhancement to be added at an unspecified point in the future. Institutions now need infrastructure that can process payments end-to-end in under 10 seconds, remain available 24/7/365, and support real-time fraud and operational controls.
Commercial pressure is growing alongside regulatory pressure. Customers increasingly expect euro payments to arrive immediately, including outside traditional banking hours. Now that the €100,000 transaction cap has been lifted, SEPA Instant can support payments of up to €999,999,999, bringing it in line with SEPA Credit Transfer and making it suitable for a much wider range of use cases.
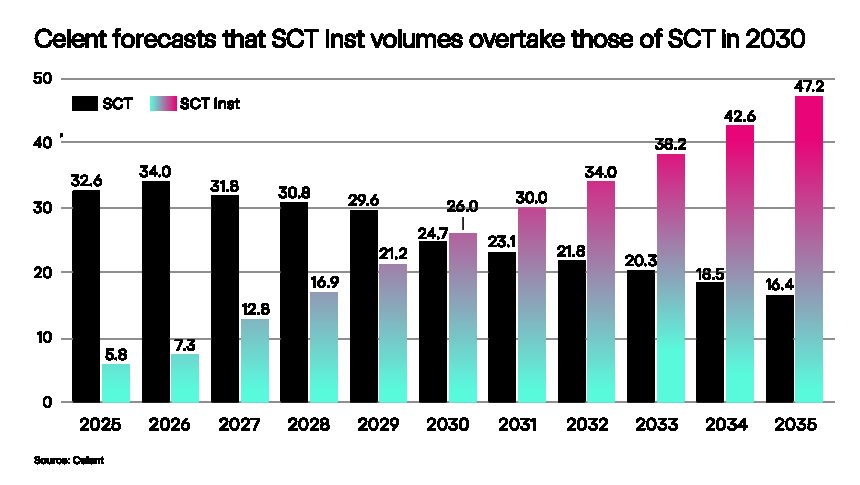
ClearBank-commissioned research by Celent found that surveyed financial institutions expect SEPA Instant to account for 75% of all SEPA credit transfers by 2035 and overtake standard SEPA Credit Transfer by 2030.
We’ll be referring to the Celent and ClearBank research throughout this article. If you’d like to read it in full for further insights: SEPA Instant Adoption in Europe.
The same research found that EMIs and PIs are less prepared than banks for SEPA Instant, with 20% surveyed expecting to miss the July 2027 requirements by three to six months.
The challenges with implementing SEPA Instant within your institution
While SEPA Instant brings speedy processing for customers, implementation can be a major investment for regulated financial institutions.
You need round-the-clock incident monitoring, customer support, fraud controls, and sanctions checks. Liquidity also becomes more complex because you need enough euro funding available outside normal banking hours.
In the SEPA Instant Adoption in Europe survey, 50% of surveyed payment service providers (PSPs) ranked operational challenges among their top three concerns, while 56% cited limited expertise or talent.
Implementation costs can also be substantial, with 78% of non-banks surveyed expecting to spend between €1 million and 10 million for SEPA Instant.
Because of these challenges, EMIs and PIs are more likely to use a bank or third-party provider rather than build every capability themselves as direct participants.
Direct vs indirect SEPA participation: What’s the difference?
Direct and indirect participants can both access SEPA schemes, but the underlying operating models differ.
A direct participant connects to the relevant clearing and settlement mechanism and manages its own settlement arrangements and adherence to the scheme.
An indirect participant connects through a sponsor bank that is already a direct member. The sponsor handles the underlying connectivity and settlement, while the financial institution may operate under its own BIC and remains reachable across SEPA.
Note: Until recently, direct participation in SEPA clearing systems was largely limited to credit institutions. Amendments to the Settlement Finality Directive introduced through the Instant Payments Regulation have broadened access for authorised payment institutions (PIs) and Electronic Money Institutions (EMIs), enabling eligible non-bank PSPs to participate directly in certain payment systems, subject to the applicable participation requirements. This means direct access is now an option for some non-banks, especially larger institutions that want more control over payment flows or expect high enough volumes to justify the investment.
If you’re still deciding which is best for your institution, here are some considerations.
Direct SEPA participation gives you more control, but requires a larger investment
Direct participants have greater control over how payments are routed, settled, and monitored. They may also avoid the fees charged by sponsor banks, which can make direct access more economical once payment volumes reach enough scale.
But gaining direct access includes significant infrastructure and investment including:
- Connecting directly to SWIFT and the relevant CSM (Clearing and Settlement Mechanism).
- Opening settlement accounts with ongoing funding responsibilities.
- Maintaining liquidity becomes a 24/7 requirement for SEPA Instant.
- Funding and defunding central bank accounts adds daily operational work.
- Managing balance sheet exposure requires specialist treasury oversight.
- Technical testing and ongoing scheme compliance.
We often see that it takes around 12 to 18 months to become a direct participant, though this varies based on your application.
Indirect SEPA participation removes much of the underlying complexity
Under the indirect participant model, your sponsor bank maintains direct scheme connectivity and completes settlement on your institution’s behalf.
Your institution can still have its own BIC and issue IBANs, but you don’t have to maintain the complete SWIFT, central bank, clearing, and settlement estate yourself.
The sponsor bank can also handle or support:
- Registration with clearing and settlement mechanisms
- Settlement-account infrastructure
- Liquidity and treasury processes
- Scheme testing and technical onboarding
- Ongoing changes to scheme requirements
Becoming a SEPA indirect participant is generally faster than direct access, but implementation timelines vary considerably, ranging from a few months to nearly a year.
Why EMIs and PIs typically implement indirect SEPA participation
While the Celent survey found that many PIs and EMIs planned to continue using a partner bank for the foreseeable future, cost wasn’t the most influential reason.
When asked to share their top three reasons for becoming a SEPA indirect participant with a sponsor bank:
- 81% cited simplicity
- 64% preferred the faster time to market
- 53% wanted to focus resources on their core services
- 53% wanted to avoid holding settlement accounts with TIPS
- 50% cited lower cost
So, when it comes to reasons for maintaining indirect participation, sponsor banks provide value in simplicity and speed, rather than because direct access is always unaffordable.
Which SEPA implementation is right for your institution?
- You process enough volume to justify the upfront and ongoing investment
- Control over settlement and payment routing is strategically important
- You already have strong treasury, compliance, and payment operations capabilities and internal expertise
- You want to reduce sponsor-bank fees over the long term
- Speed to market is a priority
- You want your own SEPA identity without running the complete infrastructure
- You’d rather focus internal teams on customer-facing products and differentiation
- You need or prefer a sponsor to support settlement, scheme onboarding, liquidity, or regulatory coordination
If indirect access is the better fit, the next step is understanding the exact processes for how to become a SEPA indirect participant.
How to become a SEPA indirect participant
While becoming a SEPA indirect participant is less intensive than direct participation, there’s still a long list of tasks involved. Many tasks can be completed in parallel, for example, beginning technical testing and integration before licencing is finalised.
1. Confirm that your institution is eligible to become an indirect participant
SEPA indirect participation is generally available to regulated financial institutions, including credit institutions, payment institutions, and electronic money institutions.
You’ll need the relevant permissions to hold customer accounts and send or receive payments on their behalf. Even if you already have the correct licence, you may still need to notify your local regulator that you intend to become a SEPA indirect participant.
Requirements vary by jurisdiction and institution type, so confirm the process with your regulator and legal advisers.
2. Decide which SEPA schemes and payment flows you need to meet your product roadmap
Before approaching sponsor banks, decide which services your proposition requires. While it may sound convenient to offer everything at once, it can impact your sponsor-bank pricing and technical integration. Your proposition might include:
- SEPA Credit Transfer
- SEPA Instant Credit Transfer
- SEPA Direct Debit Core
- SEPA Direct Debit B2B
You should also clarify whether you need to send payments, receive them, or support both directions. Scheme coverage varies between sponsor banks. For example, a bank may support receiving SEPA Instant payments but not sending them.
3. Choose your sponsor bank early to speed up the process
Sponsor bank selection shouldn’t be left until the administrative work is complete because the bank will be involved in several later stages. Your sponsor bank may help determine:
- Which clearing and settlement mechanisms (CSMs) you can use
- Which SEPA schemes you can join
- How settlement and safeguarding accounts are structured
- Which technical formats and interfaces you must support
- What testing and certification are required
- How quickly you can get to market
4. Request your BIC from SWIFT to route payments correctly to your institution
A SEPA indirect participant needs its own Bank Identifier Code so that other institutions can identify it and route payments correctly.
The BIC also allows your institution to become reachable across SEPA and issue IBANs through your own proposition. Having your own BIC doesn’t necessarily mean maintaining your own SWIFT infrastructure. The sponsor bank can provide the underlying message connectivity.
Indirect participants can request a non-connected BIC from SWIFT. This identifies your institution without requiring it to operate its own connection to the SWIFT network.
5. Apply to join the relevant EPC schemes with supporting documentation
The European Payments Council manages the rulebooks and participation framework for SEPA payment schemes. You’ll need to declare your BIC and apply for adherence to each relevant scheme.
The application normally requires supporting documentation showing that your institution has the correct permissions and meets the scheme requirements. This can include a legal opinion confirming that the required regulatory steps are completed.
Your sponsor bank or an experienced legal adviser may help you prepare the application, but you remain responsible for satisfying the EPC’s requirements.
6. Select your clearing and settlement mechanisms based on your sponsor bank’s setup
SEPA payments are exchanged through clearing and settlement mechanisms. Your options will depend partly on the CSMs your sponsor bank already connects to. You may use different CSMs for different schemes, depending on the sponsor’s coverage and your reachability needs.
The sponsor bank then registers your BIC with the relevant CSMs so payments can be routed to and from your institution.
7. Open bank accounts to protect customer funds
You’ll usually need accounts to support settlement and the protection of customer funds. This commonly includes:
- A settlement account to fund outgoing payments and receive incoming settlements
- A safeguarding account to separate customer funds in line with regulatory requirements
Many institutions open both accounts with the sponsor bank to simplify transfers and oversight, although the exact arrangement can vary.
Intraday transfers between these accounts are important. If the settlement account doesn’t contain enough funds, payments may fail or stop processing, and penalties may apply.
For SEPA Instant, you must support payments outside normal banking hours. That may require prefunding, agreed liquidity buffers, or automated funding processes to ensure the settlement account remains adequately funded 24/7.
8. Integrate with the sponsor bank systems to get up and running
Your systems must connect to the sponsor bank’s infrastructure so payment messages can travel between your platform and the CSM. Your team will need to:
- Review the sponsor’s technical documentation
- Build the connectivity
- Translate the sponsor’s message formats into your own internal formats
- Develop workflows for payment statuses, returns, recalls, rejects, and other R-transactions
You’ll also need systems capable of assigning IBANs, maintaining account balances, producing statements, and supporting the required financial crime controls.
9. Complete testing and scheme certification for a smoother launch
Before launch, the sponsor bank will test whether your payment messages conform to the relevant SEPA standards. Testing normally checks that:
- Messages you submit are correctly formatted, and messages sent back by the sponsor are processed accurately
- Payment statuses and exceptions are handled within the required timeframe
- Your systems can support the expected volume and performance
The process may include SEPA certification, stress or performance testing, and small-value production payments, sometimes called penny tests. SEPA Instant adds stricter performance expectations because payments must be processed within seconds and remain available 24/7.
10. Prepare your ongoing operating model after approval
Becoming operational is not the end of the project. You should establish operational processes and governance arrangements covering:
- Liquidity monitoring
- Payment investigations and exceptions
- Fraud prevention and detection
- Sanctions checks
- Incident management and operational resilience
- Customer support
- Scheme and regulatory changes
You should also establish escalation routes, reporting expectations, service levels, maintenance notifications, and change-management processes before launch.
Make sure to clearly outline which responsibilities sit with your institution and which sit with the sponsor bank. SEPA Instant makes this especially important because incidents, insufficient liquidity, and suspicious payments can arise outside standard working hours.
What to look for in a SEPA sponsor bank
Finding the right sponsor bank should be based on more than cost and basic connectivity. You’ll also want to consider the following:
- Check that the bank supports schemes and payment flows you need now and later. Sponsor-bank coverage can vary significantly. Some may support SEPA Credit Transfer but not SEPA Instant or allow you to receive instant payments without sending them. Also, check whether the bank can support services you may need later, such as UK payment schemes, multi-currency accounts and payments for major non-euro markets such as Poland.
- Make sure the infrastructure is genuinely built for real-time payments and scale. An API alone doesn’t guarantee that the systems behind it can process payments continuously. Ask about batch processing, planned downtime, payment-processing times, failover arrangements, incident response, maintenance windows, and performance during peak volumes.
- Understand how the bank handles liquidity, settlement, fraud, and operational support. Ask how liquidity is monitored and what happens when balances run low outside of normal banking hours, especially in the case of SEPA Instant. You should also clarify how the bank supports fraud controls and payment exceptions.
- Evaluate the developer experience and implementation support. Strong documentation and a realistic test sandbox can affect your launch timeline. Ask how quickly technical questions are answered and whether the team has experience supporting SEPA onboarding and testing.
- Clarify the full commercial model and assess the relationship long-term. Compare fees, minimum volumes, reserves, and contract terms. More than half of the EMIs and PIs surveyed by Celent said they would consider changing banks if the SEPA Instant service they received wasn’t good enough, so technology, responsiveness, and roadmap matter as much as headline pricing.
Why choose ClearBank for SEPA indirect participation?
ClearBank is an EU and UK-authorised B2B bank built specifically to support financial institutions. We hold over £18 billion in client deposits and power over 17 million accounts. Because we focus on B2B infrastructure, we don’t compete directly for your end customers.
Euro client funds are held securely at De Nederlandsche Bank and the European Central Bank, and pound sterling funds are held at the Bank of England, ensuring secure and always-on access.
Here’s why companies like Fiat Republic work with ClearBank.
Launch SEPA services faster with API-first infrastructure
ClearBank’s cloud-native API gives you a faster, simpler route into SEPA payment flows. We typically complete onboarding and integration for indirect access in around one to three months, compared with roughly 12 to 18 months for direct participation.
Detailed documentation and a sandbox environment help your developers understand the build before connecting to live services, reducing avoidable back-and-forth. Our experienced API integration team also supports testing and more complex implementation issues throughout the process.
In one recent implementation, a BaaS provider client integrated with ClearBank’s SEPA Instant API within a month, with testing and EPC preparation completed in around six weeks.
Access European accounts and payment rails through one banking partner for a simpler setup
ClearBank Europe has direct access to SEPA Credit Transfer, SEPA Instant, SEPA Direct Debit debtor, and T2, so that you can connect to multiple payment schemes with one provider. Our Dutch banking licence is passported across 21 European jurisdictions, supporting you to operate or expand across multiple markets. We’re also connected to all major UK payment schemes if relevant to your business model (Faster Payments, Bacs, CHAPS).
You can combine access to the SEPA scheme with euro accounts and the settlement infrastructure needed to support your payment flows.
Depending on your setup, ClearBank can also provide virtual accounts and vIBANs that help automate reconciliation and enable adequate customer fund administration, while funds remain in the underlying real account structure.
Process SEPA Instant payments reliably as volumes grow
Once you’re live, ClearBank’s cloud-native infrastructure helps you process growing SEPA Instant volumes without relying on legacy batch systems. We mirror our platform across separate Microsoft Azure availability zones and use an active-active architecture with dynamic failover. This helps payments continue processing if one component fails and contributes to API uptime of over 99%.
ClearBank also maintains the SWIFT estate, direct scheme connectivity, and settlement infrastructure. We manage the central-bank relationships and treasury processes behind settlement, allowing you to access SEPA Instant without operating your own TIPS account or specialist liquidity function.
Case study: How FuturePay expanded EUR and GBP collections with ClearBank
FuturePay wanted to give its enterprise clients a more local way to collect EUR and GBP across Europe and the UK. Relying more heavily on correspondent banking and cross-border wire transfers can make settlement slower, reduce payment visibility, and create more reconciliation work for businesses operating internationally.
By connecting to ClearBank’s regulated EU and UK banking infrastructure through an API, FuturePay can provide local collection accounts, virtual IBANs, and access to SEPA Instant and Faster Payments. This allows its clients to collect funds locally and settle payments faster within FuturePay’s own platform.
“Working with ClearBank is a major step forward in scaling our global local collection capabilities. It enables us to offer clients a truly localised payment experience across the UK and Europe, with faster settlement, greater transparency and more efficient reconciliation; critical for businesses operating across borders.” – Allen Cai, Founder and CEO of FuturePay.
Read the full story: FuturePay selects ClearBank to expand local GBP and EUR collections across the UK and Europe
Choose ClearBank as your SEPA indirect participant sponsor bank for speed and reliability
Indirect participation remains the preferred route for many EMIs and PIs because it offers more simplicity and faster time to market.
The sponsor bank you choose will determine how quickly you can launch and how reliably you can support SEPA Instant as volumes grow. ClearBank combines direct European scheme access with cloud-native infrastructure, API-led integration, and support from an experienced implementation team.
To explore SEPA indirect participation with ClearBank, get in touch.
FAQs
A direct SEPA participant connects to the relevant clearing and settlement mechanism itself and manages its own settlement, liquidity, technical infrastructure, and ongoing scheme obligations.
An indirect SEPA participant accesses the scheme through a sponsor bank that is already a direct member. The sponsor bank handles the underlying connectivity and settlement, while the financial institution can still operate under its own BIC and remain reachable across SEPA, while adhering to the SEPA scheme obligations
ClearBank supports SEPA indirect participation through its European banking infrastructure, helping regulated financial institutions access SEPA without building and maintaining the full direct-participation setup themselves.
SEPA indirect participation is generally available to regulated financial institutions, including credit institutions, payment institutions, and electronic money institutions.
Applicants need the relevant permissions to hold customer accounts and send or receive payments on their behalf. They may also need to notify their local regulator, obtain a BIC, and complete the required European Payments Council and sponsor-bank onboarding steps.
ClearBank works with regulated financial institutions that want to access SEPA through an indirect participation model.
The timeline varies depending on the sponsor bank, regulatory readiness, scheme scope, technical integration, and testing requirements. In general, becoming a SEPA indirect participant can take anywhere from a few months to closer to a year.
In many cases, the onboarding and integration process with ClearBank can take around one to three months, depending on the client’s readiness and implementation requirements. This can be significantly faster than pursuing direct participation, which may take around 12 to 18 months.
Look for a sponsor bank that supports the SEPA schemes and payment flows you need, including SEPA Credit Transfer and SEPA Instant. You should also assess its real-time infrastructure, resilience, settlement and liquidity support, fraud controls, developer documentation, onboarding experience, and commercial model.
The right sponsor bank should be able to support reliable 24/7 payments and scale with your transaction volumes. ClearBank combines direct European scheme access with cloud-native infrastructure, API-led integration, and support from an experienced implementation team.